Executive Summary: Core Differences at a Glance
Choosing between a Will and a Private Family Trust is one of the most significant wealth decisions an Indian family can make. Here is the distilled legal truth to guide your estate planning:
1. Fundamental Concepts: Understanding Wills and Trusts
Before comparing costs and tax benefits, we must understand the core legal difference between these two instruments. Indian succession law treats them in fundamentally distinct ways.
Under Section 2(h) of the Indian Succession Act, 1925, a Will is a legal declaration of your intention regarding your property after your death. It is an ambulatory instrument , which means it has zero legal force while you are alive.
You remain the 100% absolute owner of your assets until your last breath. You can sell, mortgage, gift, or rewrite your Will whenever you wish under Section 62. The Will only springs to life once death is legally proven.
Under Section 3 of the Indian Trusts Act, 1882, a private trust is an obligation annexed to the ownership of property. You (the Settlor ) transfer property to trusted managers (the Trustees ) to hold and manage for the benefit of chosen family members (the Beneficiaries ).
Unlike a Will, a family trust can take effect immediately during your lifetime (a Living Trust ). Legal title separates from beneficial enjoyment, allowing you to establish continuous rules that survive your death.
2. Head-to-Head Comparison: Will vs Private Family Trust
To evaluate which instrument fits your family wealth goals, examine this detailed side-by-side comparison across eleven crucial parameters:
The Core Trade-off: A Will delivers simplicity, lowest cost, and complete flexibility during your life. A Private Family Trust delivers ironclad confidentiality, protection against probate battles, and multi-generational control, but requires upfront stamp duty and ongoing accounting.
3. When a Will is 100% Sufficient for Most Indian Families
Despite marketing from corporate wealth managers pushing high-fee family trusts, the statistical reality is that more than 90% of Indian households only need a well-drafted Will. Here is why:
Setting up a trust involves legal fees of ₹50,000 to ₹3,00,000, plus recurring annual audit charges of ₹25,000+. For a modest estate, these expenses eat up hard-earned family savings without providing proportional benefit.
If your children maintain cordial relationships and you are dividing property equally or amicably, there is minimal litigation risk. A registered or witnessed Will easily settles the estate upon death.
If your children are adults in stable careers, you do not need trustees micromanaging their allowances. A one-time outright inheritance via a Will gives them direct ownership with zero bureaucracy.
Once assets are transferred into an irrevocable trust, you surrender ownership. With a Will, you retain absolute title to buy, sell, or mortgage your home at any time without asking permission from trustees.
Draft a legally binding Section 63 Will online in 15 minutes with our guided wizard.
4. When a Private Family Trust Makes Strategic Sense
While a Will handles straightforward bequests, certain complex family situations and substantial net worth brackets demand the structural protections of a Private Family Trust:
If both parents pass away, leaving assets to minor children in a Will requires legal guardianship proceedings under the Guardians and Wards Act, 1890. For children with physical or cognitive disabilities, a Will leaves them vulnerable to predatory relatives. A Private Trust appoints corporate or trusted family trustees to manage monthly allowances, medical bills, and housing without court interference.
Dividing shares in an operating private limited company among three children via a Will often causes boardroom deadlocks and destroys enterprise value. Placing operating equity into a Family Trust keeps shareholding unified under chosen managing trustees while distributing dividend income equally among heirs.
In second marriages, testators frequently worry that if they leave everything to their surviving spouse in a Will, the spouse might later write a new Will disinheriting the children from the first marriage. A trust solves this by granting the spouse a lifetime right to income or residence, while legally guaranteeing that the principal property automatically devolves to biological children upon the spouse's death.
Prominent industrialists, celebrities, and HNI families often want to keep their wealth, corporate stakes, and family agreements private. In mandatory probate jurisdictions like Mumbai, probate proceedings require public newspaper advertisements and court filings. A trust completely bypasses court probate, keeping your family's net worth 100% confidential.
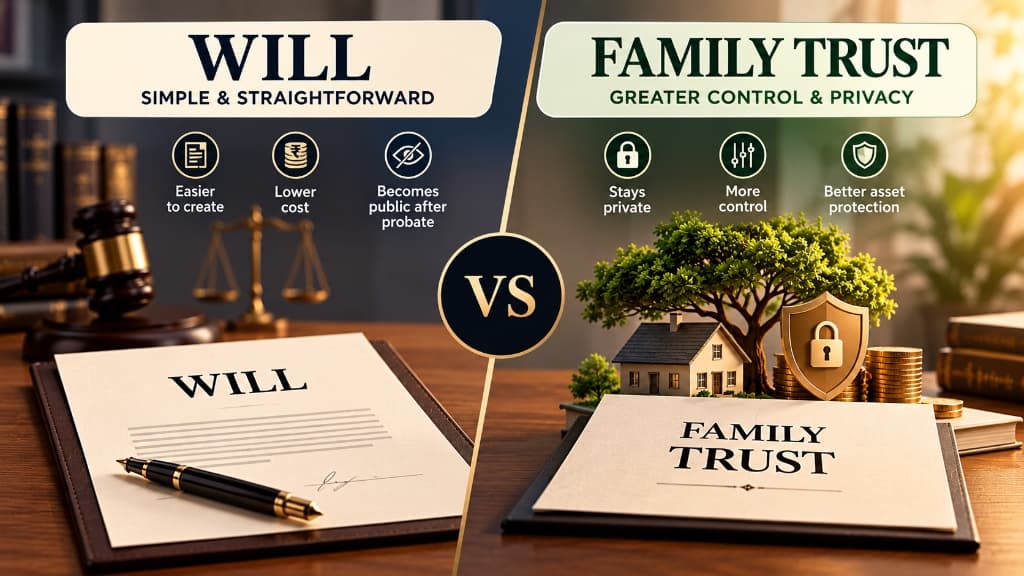
5. Visual Comparison: Will vs Family Trust Breakdown
This diagram illustrates the core dichotomy between a straightforward testamentary Will and a private family trust:
6. Trust Classifications: Revocable vs Irrevocable
If you decide that a Private Family Trust is appropriate for your family, you must choose its structural classification under the Indian Trusts Act, 1882. There are two primary dividing lines:
In a revocable trust, the Settlor retains the legal right to amend, alter, or dissolve the trust at any point. You can reclaim trust property into your personal name whenever you wish.
Limitation: Because you retain control, the Income Tax Department treats the income as yours under Sections 61 to 63 of the Income Tax Act. Furthermore, it offers zero protection against personal bankruptcy or creditor attachments.
In an irrevocable trust, the Settlor permanently parts with ownership and control of the settled assets. You cannot unilaterally cancel the trust or take back the property.
Advantage: Because the property no longer belongs to you, it provides strong asset protection against future business debts, guarantees, and insolvency proceedings, assuming the trust was created before debts arose.
In a determinate trust, the trust deed explicitly names the beneficiaries and fixes their exact percentage entitlements (e.g. 50% to Son, 50% to Daughter). The trustees have zero discretion to change shares.
Tax Benefit: Under Section 161, trust income is taxed in the hands of the trustees as representative assessees at the beneficiaries' individual personal tax slab rates, avoiding penal tax brackets.
In a discretionary trust, the trustees have complete freedom to decide when, how much, and to which beneficiary funds are distributed, based on emerging life events, medical emergencies, or education needs.
Tax Penalty: Under Section 164 of the Income Tax Act, discretionary trusts are taxed at the Maximum Marginal Rate (MMR of ~39% or 42.74%), making them tax-inefficient unless specific statutory exceptions apply.
7. Taxation Framework: Income Tax Act Sections 161 & 164
Tax planning is a decisive factor in choosing between a Will and a Family Trust. India currently has zero inheritance tax or estate duty, but income tax rules apply differently to each structure:
Tax Insight: If your primary goal is tax minimization and you have standard residential properties, a Will is vastly simpler and avoids the Maximum Marginal Rate trap that often catches carelessly drafted discretionary trusts.
8. Asset Protection: Shielding Estates from Creditors
For promoters, business directors, startup founders, and professionals facing commercial risks, asset protection is paramount. Here is how Indian courts handle creditor claims against Wills and Trusts:
Because a Will only operates upon death, your assets remain in your personal name throughout your life. If your business defaults on bank loans, recovery tribunals (DRT) or insolvency courts (IBC 2016) can attach your properties, bank accounts, and shares under Section 60 of the Code of Civil Procedure.
Even after your death, Section 325 of the Indian Succession Act mandates that the executor must pay off all your debts and funeral expenses before distributing a single rupee to your beneficiaries. Your heirs only inherit what is left over.
When you settle assets into an Irrevocable Private Family Trust, legal title transfers permanently to the trustees. The assets no longer form part of your personal balance sheet. Consequently, future personal creditors, bank guarantees, or commercial litigants cannot attach trust assets.
9. Privacy and Probate: Public Records vs Private Wealth
Many families overlook the privacy implications of estate planning until it is too late. The difference between a public probate proceeding and private trust administration is profound:
10. Hybrid Strategy: Pour-Over Wills & Testamentary Trusts
You do not necessarily have to choose exclusively between a Will and a Family Trust. Sophisticated Indian estate planners frequently combine both vehicles into a unified, leak-proof structure:
Even after settling a Living Family Trust, individuals frequently acquire new savings accounts, mutual fund folios, or inherit ancestral shares that were never transferred into the trust.
A Pour-Over Will acts as a legal net. It states: "Any property standing in my personal name at the time of my death shall be given entirely to the trustees of my Family Trust, to be added to the trust principal and administered according to its terms."
If you want trust protections for minor children or elderly parents, but do not want to pay annual accounting and audit fees while you are young and healthy, you can create a Testamentary Trust inside your Will.
Under Section 5 of the Indian Trusts Act, a trust can be created by a Will. The trust only springs into existence upon your death. During your lifetime, you pay ₹0 trust maintenance fees, while still securing milestone protections for your family when you pass away.
Will vs Private Family Trust in India
Statutory comparison under Indian Succession Act 1925 and Indian Trusts Act 1882
| Parameter | Will in India | Private Family Trust |
|---|---|---|
| Effective Date | Only upon death | Immediately upon execution |
| Initial & Annual Cost | ₹0 stamp duty, ₹0 annual fees | Stamp duty on deed + annual audit/tax filing |
| Probate & Public Record | Becomes public record during probate | 100% confidential private agreement |
| Asset Protection | Zero protection from personal debts | Strong creditor shield (if irrevocable) |
| Staged Payouts | Outright one-time transfer | Milestone payouts (e.g. at ages 25, 30) |