Quick Facts About Claiming Deceased Bank Balances in India
- UDGAM is a Search Tool, Not a Cash Counter: RBI's UDGAM portal identifies which bank branch holds the dormant account and generates a reference number (UDRN). You must visit the bank branch in person to claim the funds.
- Your Money is Never Permanently Lost: Under Section 26A of the Banking Regulation Act, 1949, deposits inactive for 10+ years move to the RBI DEA Fund. However, legal heirs retain a permanent right to claim the full principal plus applicable interest at any time.
- Nominees Get Paid in 15 Days: If a nominee was registered by the deceased, RBI rules strictly mandate that the bank settle the claim within 15 calendar days without demanding probate or succession certificates.
- Simplified Limits Without Court: For accounts without a nominee, banks allow claims up to their board-approved threshold (typically ₹1 Lakh to ₹5 Lakhs) using simple indemnity bonds, avoiding civil court fees.
- A Will Stops Orphan Accounts: Creating an itemized asset registry and matching nominations with a Will ensures your family never leaves money behind in dormant bank accounts.
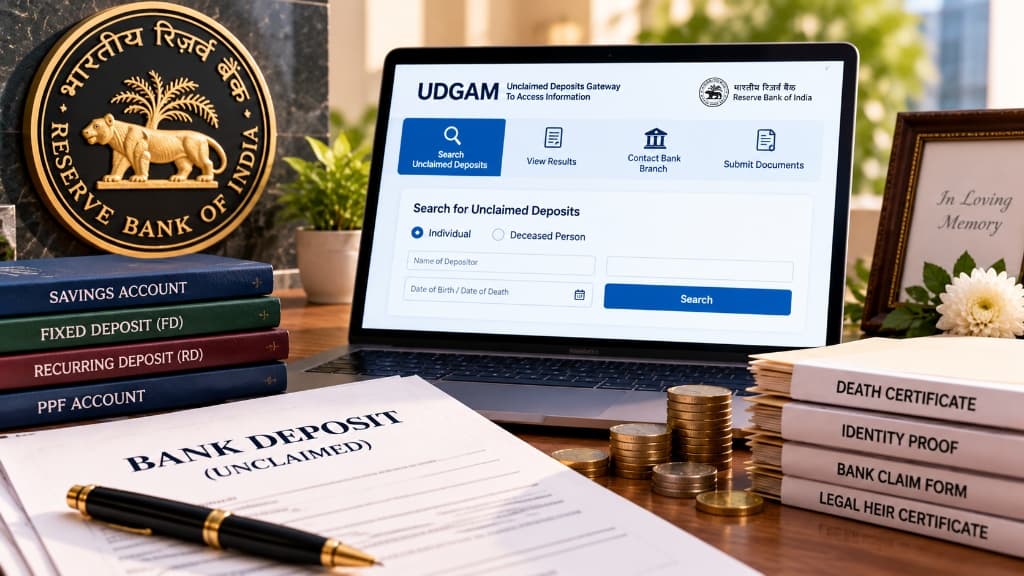
1. What is the RBI UDGAM Portal and What Does It Do?
When a loved one passes away, families often struggle to piece together their financial footprint. Old bank passbooks get misplaced, fixed deposit receipts are lost during house moves, or senior citizens quietly maintain savings accounts that their children never knew existed.
To solve this national challenge, the Reserve Bank of India (RBI), in collaboration with Reserve Bank Information Technology Pvt. Ltd. (ReBIT) and Indian Financial Technology & Allied Services (IFTAS), launched the UDGAM portal (Unclaimed Deposits - Gateway to Access inforMation).
- • Searches across 30+ major banks simultaneously.
- • Scans savings accounts, current accounts, and term deposits.
- • Generates an Unclaimed Deposit Reference Number (UDRN).
- • Reveals the exact bank name and home branch location.
- • It does NOT disburse money directly into your bank account.
- • It cannot bypass physical document verification at the branch.
- • It does not override court orders or succession rules.
- • It cannot settle disputes among rival legal heirs.
2. Scale of Unclaimed Money: The RBI DEA Fund Explained
Why does bank money become "unclaimed" in India? The answer lies in the 10-year rule enacted under Section 26 of the Banking Regulation Act, 1949.
If an operative account (savings or current) or a fixed/recurring deposit sees zero customer-initiated transactions for a continuous period of 10 years, the bank is legally required to classify the funds as an unclaimed deposit.
Section 26A and the Depositor Education and Awareness (DEA) Fund
In 2014, Parliament amended the Banking Regulation Act to introduce Section 26A, creating the Depositor Education and Awareness (DEA) Fund managed directly by the RBI. Every month, scheduled commercial banks and cooperative banks must transfer all balances remaining unclaimed for 10 years to this fund.
According to official parliamentary disclosures and RBI annual reports, over ₹78,213 Crore sits in the DEA Fund across public and private banks. When including regional rural banks and cooperative lenders, the total approaches nearly ₹90,000+ Crore. Over 80% of these accounts belonged to depositors who passed away without leaving a clear inventory or Will for their heirs.
3. Step-by-Step Guide: How to Search Deceased on UDGAM
Searching for a deceased relative's unclaimed accounts on UDGAM takes less than 10 minutes. Follow these practical steps to pull up dormant bank records:
Register on UDGAM Portal
Visit https://udgam.rbi.org.in. Create an account using your active mobile number and set a password. Verify with the OTP sent to your phone.
Select 'Deceased Person' Tab
Switch the search toggle from 'Individual' to 'Deceased Person' on the search dashboard to enable family search parameters.
Enter Legal Name & Identifier
Type the deceased person's full name as per bank records. Provide at least one matching identifier: PAN, Voter ID, Passport, DOB, Date of Death, or Address.
Select Banks & Run Search
You can select specific banks (like SBI, PNB, HDFC) or choose 'All Banks' to scan across all 30+ participating financial institutions at once.
Record UDRN & Account Details
If matches are found, the portal displays the Bank Name, Branch, and a unique Unclaimed Deposit Reference Number (UDRN). Print or screenshot this result.
Visit the Bank Branch with Documents
Take the UDRN slip, death certificate, identity proofs, and relationship certificates to the branch to initiate formal claim processing.
Senior citizens often registered accounts decades ago with slight spelling variations, or only initial letters (e.g., "R. K. Sharma" instead of "Ramesh Kumar Sharma"). If your first search returns zero results, try searching with PAN card number or Date of Birth. PAN is the most reliable cross-bank identifier.
4. Required Documents: Claiming with or Without a Nominee
Once you have identified the bank and generated the UDRN, you must assemble the claim dossier. The exact paperwork depends entirely on whether a registered nominee exists on the account.
Checklist for Registered Nominee Claim (Fast-Track 15-Day Route)
RBI Fast-TrackIf the deceased registered your name as nominee during their lifetime, the procedure is simple and cannot be delayed by bank staff.
- Deceased Depositor Claim Form (Annexure A): Signed by the nominee. Available at branch or downloadable from bank website.
- Original Death Certificate: Issued by the Municipal Corporation / Registrar of Births & Deaths (branch verifies and returns original).
- KYC of the Nominee: Self-attested PAN card, Aadhaar card, and current address proof of the nominee.
- Original Passbook / Term Deposit Receipt: If lost, a standard Indemnity for Lost Deposit Receipt on ₹100 stamp paper.
- Cancelled Cheque of Nominee: For direct electronic bank transfer (NEFT/RTGS) of the claimed amount.
5. Bank Claim Thresholds: Small Claims vs Large Claims
Under RBI directives, every bank's Board of Directors has established an internal monetary ceiling. Within this limit, branch managers can settle claims on an indemnity basis without asking grieving families to spend tens of thousands on court fees and lawyers.
| Bank / Institution | Simplified Ceiling (No Court Order) | Surety Requirement | Authority Level for Approval |
|---|---|---|---|
| State Bank of India (SBI) | Up to ₹5,00,000 | Two independent sureties of equal net worth | Branch Manager / AGM |
| Punjab National Bank (PNB) | Up to ₹2,50,000 / ₹5,00,000 | One or two solvent sureties | Chief Manager / Circle Office |
| Bank of Baroda (BOB) | Up to ₹2,50,000 | Two sureties with income proof | Branch Head / Regional Head |
| Canara Bank | Up to ₹2,00,000 | One acceptable surety | Divisional Office / Branch Head |
| HDFC Bank & ICICI Bank | ₹1,00,000 to ₹5,00,000* | Based on customer risk categorization | Cluster Head / Nodal Officer |
*Note: Bank board policies are revised periodically. Always request the specific bank branch's latest Deceased Depositor Claim Policy circular before executing stamp papers.
6. Claim Process by Account: Savings, FDs, RDs & PPF
Different financial products have distinct interest calculation rules and operational procedures when transferred to the DEA Fund:
Once marked inoperative, savings accounts continue to earn regular savings interest until they hit the 10-year mark. After transfer to the DEA Fund, the RBI specifies a statutory interest rate (currently around 3% per annum). Current accounts do not earn interest unless held under specific court-mandated escrow arrangements.
Term deposits earn the agreed contractual interest until their maturity date. If the deposit is not renewed or claimed after maturity, banks apply the prevailing savings account rate or contracted rate (whichever is lower) under RBI master directions until transfer to the DEA Fund. Both principal and interest are refunded upon claim.
PPF accounts mature after 15 years. Upon the death of the subscriber, the account cannot be continued by legal heirs; it must be closed. Under PPF Scheme 2019 rules, interest continues to accrue at the post-office savings rate until closure. Claims are filed at the managing post office or bank branch using Form G (nominee) or Form H (legal heirs).
If an operative account linked to a bank locker becomes dormant and rent is unpaid, banks follow RBI locker breaking guidelines. Breaking is conducted before independent witnesses, a panchnama and video recording are executed, and inventoried contents are sealed in an envelope for the legal heirs or court-appointed executor.
7. Head-to-Head Comparison: Three Bank Claim Pathways
Understanding which route your family qualifies for is essential before you spend money on stamp paper, affidavits, or legal counsel:
| Feature | 1. Nominee Route | 2. Simplified Indemnity | 3. Succession Certificate | 4. Registered Will |
|---|---|---|---|---|
| Who Can Claim? | Registered Nominee on bank records | All Legal Heirs jointly (or 1 heir with NOCs) | Legal Heirs named in Court Certificate | Executor or Beneficiaries under Will |
| Court Order Needed? | No court order required | No (Settled under Bank Board Policy) | Yes (Succession Certificate Part X ISA) | No (Unless probate mandated / challenged) |
| Applicable Balance Limit | Unlimited amount | Up to bank threshold (e.g. ₹1 Lakh to ₹5 Lakhs) | Above threshold or disputed balances | Unlimited estate value |
| Legal Status of Recipient | Trustee / Custodian for legal heirs | Beneficial owner as statutory legal heir | Court-recognized legal successor | Absolute beneficiary under testator wishes |
| Indemnity Bond Required? | No (Only standard receipt / claim form) | Yes (Stamped bond with 1 or 2 sureties) | No (Court administration bond already filed) | Executor discharge receipt |
| Settlement Timeframe | Strictly 15 days (RBI Mandate) | 30 to 45 working days | 6 to 12 months in court + 15 days bank | 15 to 30 days upon executor verification |
| Risk of Family Disputes | High (Heirs can sue nominee trustee) | Medium (Requires NOC from all known heirs) | Low (Binding court decree with citation) | Very Low (Clear written testamentary intent) |
8. Timeline Expectations: How Long Does Settlement Take?
How quickly will the bank transfer the money to your account? The answer depends strictly on documentation completeness and regulatory deadlines:
Crucial Consumer Right: You do NOT have to wait for the RBI to release money to the bank. The bank is legally obligated to settle your verified claim from its own liquidity first. The bank later files an internal monthly claim for reimbursement with the RBI DEA Fund.
9. How a Will and Matched Nominees Prevent Frozen Money
Why did over ₹78,000 Crore end up stranded in the DEA Fund in the first place? In 95% of cases, it happens because of two simple mistakes:
Family members had no single document listing where the deceased held bank accounts, FD certificates, or demat holdings.
The nominee was either never added, had predeceased the account holder, or differed from what the legal heirs expected.
Don't Let Your Hard-Earned Savings Sit in the RBI DEA Fund
Drafting a legally binding Will on WillDrafting.in takes just 15 minutes. It lets you catalog all your bank accounts, name an Executor empowered under Section 211 of the Indian Succession Act, and align your bank nominations with your true heirs.
10. Common Rejection Reasons and How to Avoid Them
Bank legal departments reject roughly 25% of first-time deceased depositor claims due to avoidable clerical errors:
If the deceased is recorded as "S. P. Gupta" in the passbook but "Satya Prakash Gupta" on the death certificate, submit a Notarized One-and-the-Same Person Affidavit along with supporting Aadhaar/PAN history.
Under Hindu Succession Act amendments and Supreme Court rulings (Vineeta Sharma 2020), married daughters are equal coparceners and Class 1 legal heirs. The bank will reject claims if daughters are omitted from the claim form or disclaimer NOCs.
Most banks mandate that the sureties signing the Indemnity Bond must be independent third parties (not heirs receiving the money) with verifiable income proofs or real estate ownership.
11. Legal Framework and Official Statutory Citations
- Banking Regulation Act, 1949: Section 26 (Return of Unclaimed Deposits), Section 26A (Depositor Education and Awareness Fund), Section 45ZA to 45ZF (Nomination Facilities).
- RBI Master Directions: Master Direction on Settlement of Claims in respect of Deceased Depositors (DBOD.No.Leg.BC.95/09.07.005/2004-05 & subsequent updates).
- Indian Succession Act, 1925: Section 211 (Character and property of executor or administrator as such), Section 213 (Right of executor or legatee when established), Part X (Sections 370-390, Grant of Succession Certificate).
- Supreme Court of India Precedents: Shakti Yezdani v. Jayanand Jayant Salgaonkar (2023), Smt. Sarbati Devi v. Smt. Usha Devi (1983) 1 SCC 500, and Ram Chander Talwar v. Devender Kumar Talwar (2010).
Frequently Asked Questions: Claiming Deceased Deposits
Find clear statutory answers to common questions about claiming unclaimed money from UDGAM and the RBI DEA Fund.